
Move over cryptocurrencies, meme stocks and AI. The market everyone seems to be talking about, especially over the third quarter of 2026, is the bond market. On Oct. 7, the 10-year U.S. Treasury yield climbed above 5.35 per cent, marking its highest level since 2002, while the 30-year bond hit 5.7 per cent.
Liam O’Sullivan, head of client and product solutions at RPIA Capital Management, is closely watching events unfold. As a CFA Charterholder who shapes the Toronto-based firm’s distribution priorities, he finds it unusual that bonds are attracting the kind of attention typically reserved for equities.
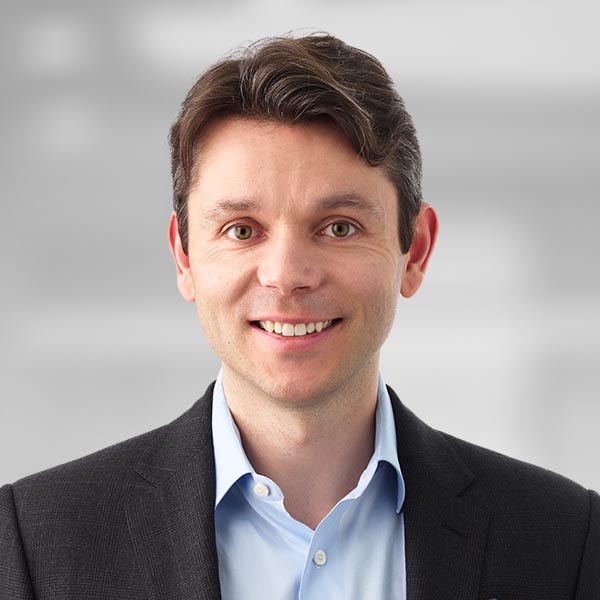
Unusual, but not necessarily troubling. “We view what’s happening as fairly healthy, and as an opportunity for investors,” O’Sullivan says.
Four points to remember when navigating fixed income
The financial environment has significantly changed, O’Sullivan says, and family office portfolio allocations should change with it. “In this past decade of low yields, family offices tended to overweight equities and private markets. But now, we are in a very different environment. Interest rates are rising, geopolitical tensions abound, and the new Chairman of the U.S. Federal Reserve [Kevin Warsh] has an ideology that is different from his predecessors. Family offices need to adapt.”
While equities performed very well over the past decade, O’Sullivan says they might not offer the best returns for the next five to 10 years. In his experience, clients and family offices that are moving money back into fixed income and credit markets are achieving a more neutral stance in the process. This provides balance and protection against what might happen in the future.
A less transparent Fed Chair sets the stage for a situation where active management is important, and portfolio managers need to react quickly to opportunities.
Liam O’Sullivan
According to O’Sullivan, fixed income and credit provide income, liquidity, diversification and capital preservation to portfolios. “When family offices start allocating the fixed-income portions of their portfolios to all achieve all four of those things, they gain durability and strength.”
Would it make sense to just leave the fixed-income portion of the portfolio in cash? O’Sullivan thinks not: “Having some cash on hand can help you take advantage of opportunities when markets get dislocated, but there are two reasons against holding a sizable portion of cash right now. The first reason has to do with maximizing yield by extending a bond’s duration. You can earn four percent or more on two-year corporate bonds in Canada right now, and five-and-a-half per cent in the U.S. The second reason is potential for capital gains. The market is pricing in three-to-four interest rate hikes in the U.S., and four-to-five in Canada by the end of 2027. We think it could be less. By locking in yields today, you could get a reasonable yield plus capital gains if central bank rates aren’t raised as much as expected.”
Investors must adapt to a changed world
Over the past year, credit markets have shifted significantly. O’Sullivan and the team at RPIA point to two major changes that fixed-income investors might not fully appreciate.
The first is the sheer volume of issuances by hyperscalers looking to fund artificial intelligence. “In investment-grade credit markets, AI issuers account for 15 to 16 per cent of corporate bonds in the U.S., which has changed the very structure of the market. Now, if you own a corporate bond fund that tracks the index, chances are you are overweight AI, whether you want that or not.”
The second change O’Sullivan has noticed is that the quality of high-yield bonds has improved. “BB or higher bonds are north of 50 per cent of the index. Investors are surprised, but now, the high yield market in the U.S. is of higher quality, and cleaner than it has been in a while with more borrowers sourcing financing from the private credit markets.”
With yields being high and spreads narrow, O’Sullivan argues for more interest rate risk and less credit risk. “In all client conversations, we hear that spreads are tight. At headline levels, yes. But if you peel back layers of the market, there is a lot to get excited about in public and private credit. We are opportunistic.”
Active management for the win
If family offices choose the passive route, they could miss out on various opportunities, O’Sullivan says, adding that the very composition of corporate bonds has changed. “The most noteworthy aspect is the issuances in AI, where we are being selective and opportunistic and waiting for cheaper prices. But beyond that, this is an environment where there is volatility and there will continue to be volatility.”
This volatility stems from “a less transparent Fed Chair,” which “sets the stage for a situation where active management is important, and portfolio managers need to react quickly to opportunities,” he says, adding that credit managers beat the benchmark at far higher rates than government bond and equity managers.
What should family offices do?
According to O’Sullivan, family offices should look at their fixed income and credit buckets like large institutions do. The first and most fundamental question that investment committees should ask is, “How much fixed income and credit should the family office have?’ There is no one answer, as it depends on the objectives of the family office. RPIA works with clients who have a 100 per cent allocation to fixed income and credit, and also with clients who have a 15 per cent allocation.
“Many family offices have been underweight in fixed income and credit in the past decade, but is that prudent for the next decade? Where should you be? Once the client decides what the allocation towards fixed income and credit should be, then they can think about what to put in it,” O’Sullivan says.
The team at RPIA has seen a lot of demand from clients for tax-efficient short-term bond funds, with O’Sullivan himself favouring a flexible “best ideas” approach to credit that is designed to embrace opportunities when they present themselves, and step back when the idea is too expensive.
The other question that investment committees should consider pertains to active management. “In the environment we are in, would a passive income provide diversification? Are you taking on more risk? Perhaps it makes sense to partner with a specialist, an active manager who could work with the clients’ individual needs to provide better risk-adjusted returns,” O’Sullivan says.
For family offices, the message is clear: The fixed-income strategies that worked over the past decade may not be suited to the next. Higher yields, shifting market dynamics and ongoing volatility are creating both challenges and opportunities, making it increasingly important to revisit portfolio allocations and take a more selective approach to credit. As O’Sullivan sees it, the goal isn’t simply to capture attractive yields, but to build a fixed-income portfolio that delivers income, liquidity, diversification and capital preservation while remaining flexible enough to capitalize on opportunities as they emerge.
Disclaimer: This story was created by Canadian Family Offices’ commercial content division on behalf of RPIA Capital Management, a member and content provider of this publication.