
Family offices fulfill a number of roles, from enterprise and wealth management, investing and tax matters to governance, philanthropy, and estate and legacy planning. As Canadian business families expand across generations and establish these formal structures, the investment advice that single-family offices provide brings a focus on a special consideration: whether they need to be registered with provincial securities regulators as portfolio managers.
It’s perhaps not as simple as it seems.
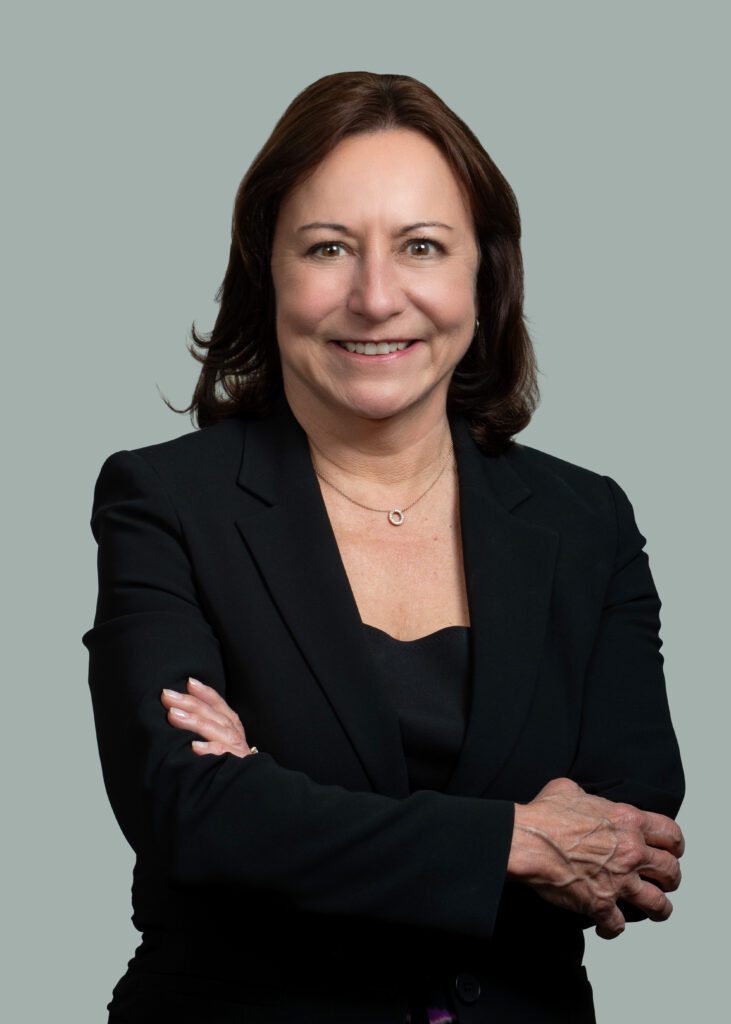
“The family office label alone doesn’t answer the registration question,” says Katie Walmsley, president of the Portfolio Management Association of Canada (PMAC), whose members include 320 asset and portfolio managers—family offices among them. “Much depends on whom the office serves and what it is actually doing.”
A non-profit organization, PMAC provides compliance support through educational conferences and networking opportunities to help members keep up to date with regulations and industry best practices.
“Many single-family offices take the position that they don’t need to register because they are managing one family’s affairs rather than advising outside clients. Where that line falls is not always clear,” Walmsley says. “For an office looking beyond the original family to serve other families or accept outside capital, however, registration can be more than a compliance requirement. It can provide a framework for growth, stronger governance and consistent reporting.”
When registration becomes necessary
That was the case for Viewpoint Investment Partners, a specialized investment management company in Calgary for family offices and ultra-high-net-worth families that in 2016 grew out of an SFO, Viewpoint Group.
Rob Van Wielingen, who is president, CEO and portfolio manager of the investment firm and is also responsible for running the SFO, says registration became necessary when Viewpoint Group began accepting outside capital into a series of specialized funds it manages. Viewpoint Investment Partners registered with the Alberta Securities Commission—a move that Van Wielingen says can be expensive and time-consuming.
“You have to set up an entire compliance framework,” he says. “If you’re a single-family office for your family—siblings, parents, cousins, holding companies, trusts, foundations—that’s all non-arm’s-length capital that you’re managing, and there’s no reason to be under the regulatory environment.”
Some SFOs aspire to grow and accept outside capital into their strategies, Van Wielingen says, but many of those are real estate or private equity partnerships that don’t have to be registered. “We’re unique in that the strategies that we offer are in securities and we have prospectuses and they’re in liquid markets,” he adds.
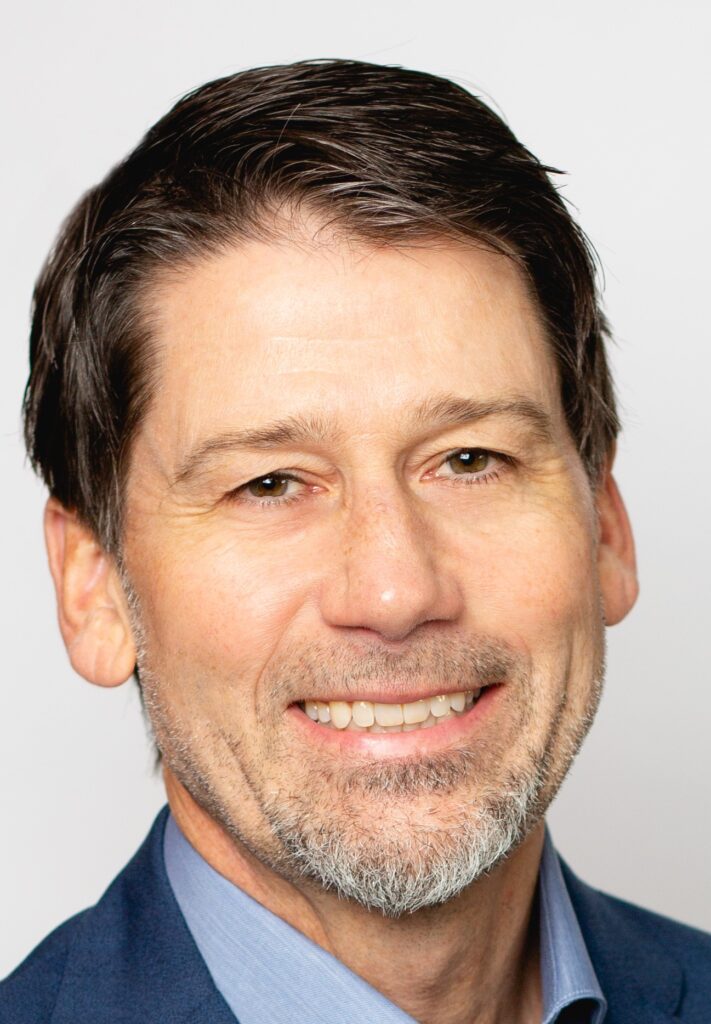
Jason Brooks, a partner and Vancouver regional leader of the investment management group at law firm Borden Ladner Gervais, says the trigger for registration “is when a firm is in the business of advising others with respect to buying and selling securities.”
Brooks, who supports clients across the country and internationally doing business in Canada on securities regulatory matters, points out that there is “a principles-based assessment required to determine whether the registration is required. There’s no black-and-white lines that are drawn and no published regulatory guidance applicable to family offices.”
He says three “exemption orders” have been issued recently by provincial regulators stipulating that “registration as an advisor is not generally required where the advising activities are confined to a single family.”
What the process looks like
What’s involved in registration? Brooks says a firm must prepare a detailed application with a significant set of supporting materials, including a policies-and-procedures manual and audited financial statements. “You file the application with the regulator in the jurisdiction where your head office is located,” he explains, and that is reviewed in a comment-and-response process. Registration typically takes up to 12 months and is permanent, but it is subject to the payment of fees on an annual basis. “In addition,” Brooks says, “the ongoing operation of a registered portfolio management firm involves compliance with a set of rules requirements that involve time and costs.”
There are investor protection benefits that come with registration, “but I think most family offices would say, ‘We’re going to act in our best interest, we’re going to do the right thing for our family, so we don’t need to comply with specific requirements.’”
One issue for SFOs as families evolve and grow is that “often it’s difficult to assess where the family starts and ends,” Brooks says. “Because of the nature of the registration trigger being ‘principles-based,’ there’s no bright line to say, ‘Okay, now we’ve crossed it, we need registration.’”
Walmsley notes that many SFOs “manage the managers,” by co-ordinating the family’s relationships with third-party portfolio managers. “They may arrange introductions and meetings and help co-ordinate the selection process,” she says. Whether this triggers registration depends on the role the family office plays and whether it is itself providing investment advice.
Registration brings significant ongoing compliance obligations, Walmsley points out, including specific governance, insurance, client reporting and other regulatory requirements. That’s consistent, she says, with a growing awareness of the need for proper governance within family offices. “That’s a positive development,” Walmsley adds. “Whether a family office is registered or not, it can benefit from best practices in the industry.”
There are upsides to registration, Van Wielingen says, chiefly the fact that it supports Viewpoint Investment Partners in taking advantage of the business opportunity of accepting outside capital. It also increases the company’s “standard of management and governance and oversight in how the funds are being managed.”
The benefits to investors
There are special protections for investors, he notes; for example, one regulatory requirement is for the registrant to maintain a certain level of working capital. If a manager goes below that, “you go into what’s called an early-warning system, and the securities regulator gets involved in making sure your investors are protected.”
Family offices can also realize a “reputational or a brand benefit when you’re a regulated portfolio manager and you’ve gone through a due-diligence process,” Van Wielingen adds. “You have a certain standard of internal controls and governance that gives your investors more confidence.”
Walmsley points out that registration means family offices can expand their investment management services beyond the original client family, “which will lead to growth in the business and economies of scale.”
She says there’s “continuing evolution of regulation in this industry, with a desire to optimize investor protection.” And she expects that with the growth in family offices and multi-generational wealth transfer, “there are going to be a growing number of firms that are becoming registered.”
Brooks says his office has been getting calls from new and existing SFOs asking, “‘We’re trying to assess whether we need to get registered or not—what do you think?’”
Families should monitor regulatory developments, he says. “Each family office should be making its own assessment as to whether its activities would trigger the application of securities law registration requirements, in particular where its activities cross multiple families.”
Going forward, he expects to see provincial securities regulators provide further guidance. “I am encouraging the regulators to publish something in writing that says, ‘This is our position with respect to the application of the registration requirements to family office businesses,’” Brooks says. “It would be beneficial to know where the regulators view the line.”
Mary Gooderham is a writer, editor and communication advisor based in Ottawa. She leads Cohen Gooderham Communications and has worked as a journalist for more than 40 years at The Globe and Mail, as a recording officer at the International Monetary Fund and as a custom content creator for online and print media. She’s been a contributing writer at Canadian Family Offices for four years, focusing on investment strategy, trusts, philanthropy, women in finance and estate planning.
The Canadian Family Offices newsletter comes out on Sundays and Wednesdays. If you are interested in stories about Canadian enterprising families, family offices and the professionals who work with them, but like your content aggregated, you can sign up for our free newsletter here.
Please visit here to see information about our standards of journalistic excellence.