
Our MFO special report, presented by PBY Capital, continues with this global look at best practices.
Family offices are as unique as Canadian families. They share commonalities, yet their design and structure vary. That is largely because family offices involve families of different individuals, who come into wealth in a variety of ways and for a variety of reasons, and who have specific needs. And across the industry, there is a clear line of demarcation between single- and multi-family offices; the former exist to support one family, while the latter are tasked with providing similar supports and services to multiple families at scale.
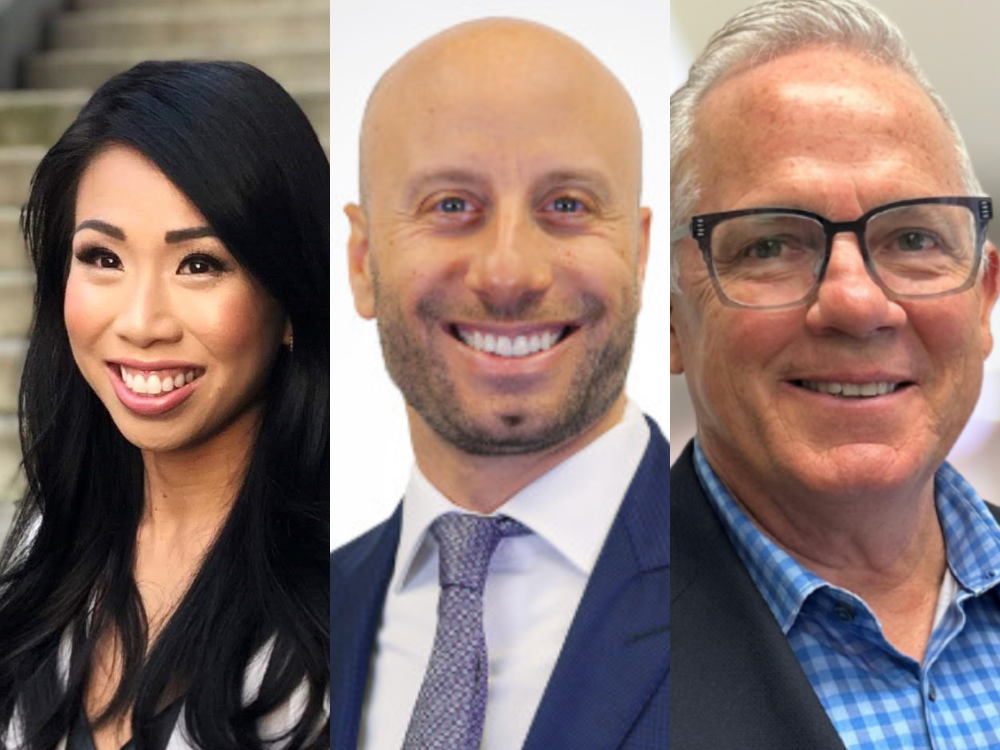
But from a client and from an operator’s perspective, are there certain processes and qualities that will define success for family offices of all stripes? Canadian Family Offices spoke with three family office leaders across the country about global best practices, and many of their insights can be applied to both a multi-family office and a single-family office. Here’s what the leaders said.
Why does the office exist?

Dan Riverso, chief executive officer with Jesselton Capital Management in Toronto, says the decision to start a single-family office is often sparked by one of two factors: the accumulation of tremendous wealth from an operating company, or from a business or real estate asset sale; or matriarchs and patriarchs “getting older and realizing, ‘What happens to the wealth we’ve built after I am gone?’”
A family office discussion does not start with a few million dollars, Riverso says. It begins with tens of millions at least, if not a minimum of $100 million for a single-family office.
For multi-family offices, the calculus is different. As Canadian Family Offices‘ annual MFO survey suggests, many multi-family offices serve families whose net worth falls well below $100 million—and even below the often-cited $30-million threshold for ultra-high-net-worth—while others support families with wealth well above that. Among MFOs, there can also be a wide variance in services delivered, but in general their goal is to replicate SFO-level support (and, of course, to turn a profit).
One challenge in Canada today is that the family office structure—in both the SFO and MFO context—is still a relatively novel concept, says Lauren Manteuffel, a family office executive and strategic advisor with Manteuffel Advisory in Vancouver. “Canada’s family office market is newer compared to the U.S., and certainly [compared to] Europe, where these have been around for multiple generations.”
For ultra-wealthy Canadian families who are considering establishing a family office or signing on with a multi-family office, there are some common best practices that they can keep in mind when making their decision.
Vision
The first step when considering establishing a family office, or for existing ones seeking a best-in-class structure, is the question of vision, says Patrick O’Connor, senior advisor and chief executive officer of Blackwood Family Enterprise Services in Winnipeg. “Start with: ‘Why do you want a family office, and what’s its purpose?’”
It’s about more than managing money. Riverso notes that many single-family offices immediately begin deploying capital following a liquidity event, and then afterwards families recognize the need to do more, which requires additional structure. Revisiting the “why” and purpose of a family office typically arises when families add more generations, requiring mentorship and guidelines around family capital.
For MFOs, the “why” applies more to the purpose of wealth than to the office itself, but they still need a vision that separates them from the crowd—and be able to communicate that to client families. From there follow many of the same structures, processes and conversations should follow.
For instance, older family members often worry about “a shirtsleeves to shirtsleeves scenario,” Riverso notes, and that can lead to discussions about goals for business ventures, philanthropy, funding lifestyle needs, and expectations for family roles and responsibilities.
Governance
With a vision comes the need for governance. “It is very important, especially as family offices become more sophisticated, where it’s not just the family and a couple trusted people,” says Manteuffel.
Governance is effectively “putting pen to paper” regarding the family vision for wealth and the rules to keep goals on track from one generation to the next, says O’Connor.
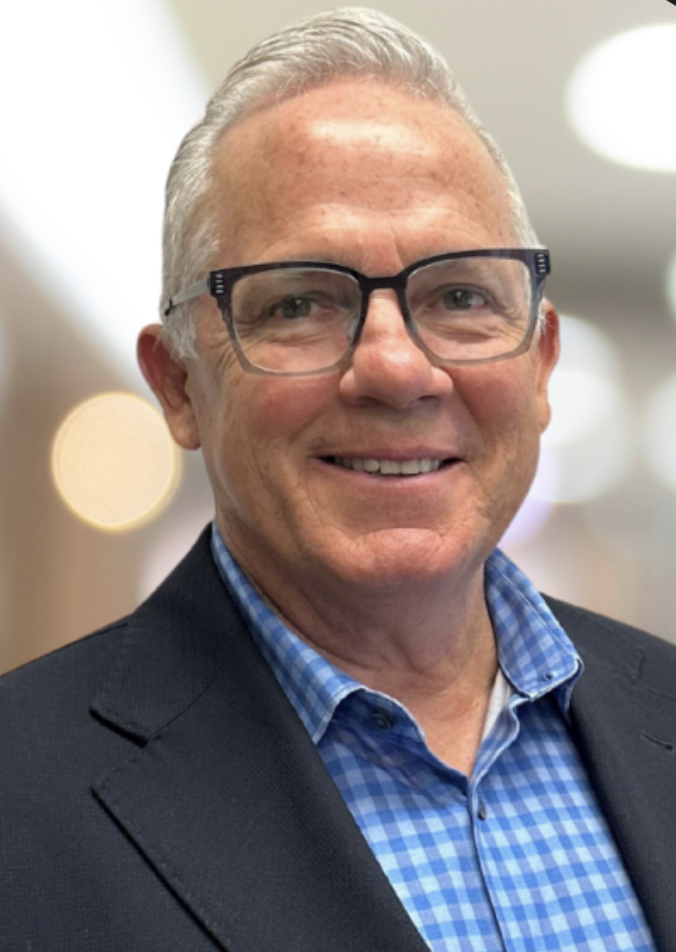
Typically, best practices involve creating documents, most notably a family charter or constitution. “It outlines the rules for decision-making, who the advisors are and what committees will be established,” says Riverso.
Think of it like launching a business, which wouldn’t (or at least shouldn’t) happen without a business plan. Too often, families view the single-family office as a cost with little financial return. Riverso says they should think of it more like a foundation or pension plan, whose design should likely emphasize longevity and capital preservation.
Multi-family offices will typically guide families through establishing clear governance processes and documentation. In the annual MFO survey, governance support falls into the most often provided category of services offered—by about four in five firms.
People
When it comes to advice and decision-making, working with the right people is obviously key. But the organizational resources a single-family office requires can often be a deciding factor in whether a family turns to a multi-family office instead.
For a single-family office, establishing governance processes typically will requiring setting up a board and committees, which may be tasked with developing and overseeing rules for everything from investments to operating companies to philanthropy, according to Riverso.
“The board might just be the family members,” he says. “And then committees might incorporate a few family members, people working in the family office, and trusted advisors.”
A good standard for committees involves including trusted advisors who are “independent from the family,” especially on the investment committee, who can help develop, for example, an investment policy statement, Manteuffel says. “The relationship aspect, especially for senior hires, is really important because this is so personal, and it’s really the family’s legacy.”
Some families hire dedicated family office personnel to oversee the investment portfolio and its many sub-managers, along with staff involved in the day-to-day administration ensuring the six “functional areas of a family office” are supported, Riverso says: investments, tax, legal, philanthropy, governance, and concierge services.
Yet many family offices contract out roles, too. “For single families, maybe they don’t need someone full-time in those roles,” Manteuffel says. (Her firm, for example, provides fractional executive services.)
A family may need the family office structure and its services, but they may not have the size (e.g., several generations and operating businesses) or enough wealth to justify a single-family office. “That is when they look to the multi-family offices,” Riverso notes, “because MFOs provide all those different services.”
It’s not so much about composition, which can change, but defining the family office’s reason to exist in the first place.
Dan Riverso
Technology infrastructure
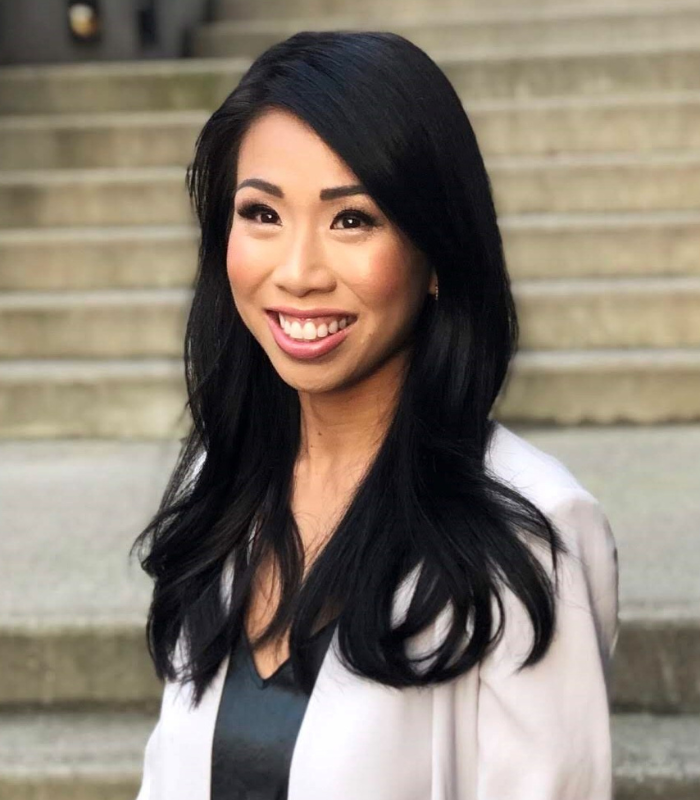
As with any enterprise, the infrastructure needs of a family office often go beyond physical space for employees, meetings, and so on. “A big part of structure today is technology, be it for investment, accounting or legal reporting,” Riverso notes.
For a single-family office, ensuring that technology is secure and efficient may require hiring in-house information technology specialists or a third-party provider; multi-family offices may or may not have these staff on hand as well. For both, tech policy statements that address cybersecurity and privacy standards and processes are critical. As well, the office should clearly define how family members and advisors use personal devices in family office operations.
“One big concern is privacy, because family offices obviously have a lot of sensitive data,” says Riverso. Today, an additional concern is artificial intelligence, he adds, and a tech policy statement should address how AI will and will not be used, along with appropriate safety guardrails.
A key challenge, even for offices with solid practices and processes in place, is that a best-in-class family office technology platform has yet to emerge. “This has been a pain point in Canada,” says Manteuffel.
Several U.S.-based platforms exist, but they are generally not geared toward Canadian family offices and the unique tax and legal rules they must follow, she adds. “That is a topic that comes up all the time in our peer group: finding something they feel really serves their family.”
Flexibility
Single-family offices can theoretically operate in isolation because they are focused on just one family. But in practice, they usually need to build a network, not just of trusted professionals, but also of other family offices, Manteuffel notes. “Historically, family offices have flown under the radar, but with peer groups, for example, you’re meeting with one another and learning about best practices,” she says.
MFOs and their clients, too, can benefit from extensive professional networks, because the landscape for family offices—still in its relative infancy in Canada—is rapidly evolving.
One venue for networking, she adds, exists in Vancouver for professionals serving family offices. It’s a place to share for new ideas and growth, which is critical because, as O’Connor notes, family offices are generally not static. Many may start with investment management as their core offering, he says, only to add on more duties “as the need for sophistication grows.”
Riverso says that is why vision is so important: to provide direction while grasping the need for flexibility as situations change. “It’s not so much about composition, which can change,” he explains, “as about defining the family office’s reason to exist in the first place.”
Joel Schlesinger is a Winnipeg-based freelance writer who has written for Canadian Family Offices since 2021. Specializing in investment, wealth advice, real estate and personal finance, he is also a regular columnist for the Winnipeg Free Press, and his work regularly appears in The Globe and Mail, Calgary Herald and Edmonton Journal.
Get our new quarterly newsletter about real estate: Canadian Family Offices’ new newsletter will bring you key insights, trends and expert perspectives. Click here to subscribe.
Please visit here to see information about our standards of journalistic excellence.