
The United States remains a key allocation for many Canadian family offices’ investment portfolios. Yet, as highlighted in Part 1 of this two-part feature, quite a few Canadian investment managers are increasing international exposure for a host of reasons, including Trump and tariffs.
Now the question is: Where are they putting their money? In Part 2 of the series, the same three Canadian capital managers discuss where they see opportunity beyond our southern neighbour’s border.
‘We love the Canadian oil and gas market right now’
Calgary-based family office Viewpoint Investment Partners sees the demand for energy, in all its forms, accelerating amid geopolitical tensions and the rapid expansion of artificial intelligence. Notably, it is allocating capital to the nation’s traditional energy sector, says Rob Van Wielingen, president and chief executive officer of Viewpoint.
“We love the Canadian oil and gas market right now,” he adds.
The direction of government, particularly at the federal level, suggests a more energy-industry-friendly stance, supporting growth into new markets overseas, he says. “I’m of the conclusion that over the next 10 years we will see a significant paradigm shift for investing in Canada.”
He expects that change will involve eliminating redundant regulation and focusing on shorter approval times for projects. Van Wielingen points to activity in the private oil and gas market as evidence he is not alone in this view.
Even U.S. investors “share a growing sense of optimism” that is drawing capital to Canada’s energy sector, he adds. The outlook is not based only on high commodity prices, he says, adding that a soaring price of oil is unhealthy and unsustainable for the industry and the global economy.
Recent disruption of traditional supply lines through the Middle East is leading more investors to look to Canada as a trusted energy partner, he says.
The recent announcement of another pipeline to the West Coast, designated by the federal government as a project of national interest, is further proof of strong momentum for the industry.
Canada’s oil and gas sector has among the highest environmental, social and governance standards in the world and an abundance of supply, and it operates under rule of law and increasingly with a social licence to produce and deliver oil and gas to its partners and Canadians, notes Van Wielingen. “It’s really an exciting time to be in the Canadian oil and gas business.”
Earnings growth not just a ‘U.S. phenomenon’
The U.S. equities market and its economy have been the engine of global growth for several years. Recently, lofty expectations around AI have powered that growth. That growth story is now spilling beyond U.S. borders, says Trevor Hunt, chief investment officer and head of strategic growth at Our Family Office Inc.
“When you look at earnings growth potential, it’s not just a U.S. phenomenon,” he says. “It’s happening in Japan and in Europe, and so we are diversified as a family office across these geographies.”
Europe’s growth is more diversified than in the U.S., though AI will help fuel earnings increasingly across all industries, he adds.
In a recent report, UBS forecasts Europe will see 15 per cent earnings growth this year, driven by banks, consumer discretionary, healthcare, industrials and information technology. It further notes that Asia could see 72 per cent earnings growth, excluding Japan, largely supported by AI supply chain needs.
UBS forecasts Japan will also see strong growth, driven by AI, corporate structural changes and other tailwinds. One recent report from The Japan Times notes its equity market has already seen 30 per cent earnings growth year over year to the end of September.
Hunt acknowledges the U.S. outlook remains strong. The S&P 500 is expected to see 25 per cent growth this year, based on a recent FactSet Insight report. Yet he adds that global markets are “in the early innings of international businesses experiencing strong price growth” powered by AI’s growth.
In particular, Taiwan and South Korea, home to leading AI hardware companies like Taiwan Semiconductor Manufacturing Corp. and SK Hynix, a leading producer of memory chips, stand to benefit.
“We are not stock pickers, so these are companies that would be in a diversified basket of international securities we own,” Hunt says. He notes the family office is now in talks with active managers in these markets, recognizing that emerging markets tend to be more inefficient than the U.S. equity market.
“We believe that as AI’s winners and losers become clearer, you can really benefit from a skilled stock picker in that environment,” says Hunt.
‘Global supply chains are upside down.’ Can Canada take advantage?
Canada has many qualities that could make it a global economic powerhouse for decades to come. Chief among them: ample natural resources.
The question—as many investors have long asked—is whether Canada can develop these strengths in a reasonably timely manner, says Peter Jessiman, CEO at Jessiman Family Investments in Winnipeg.
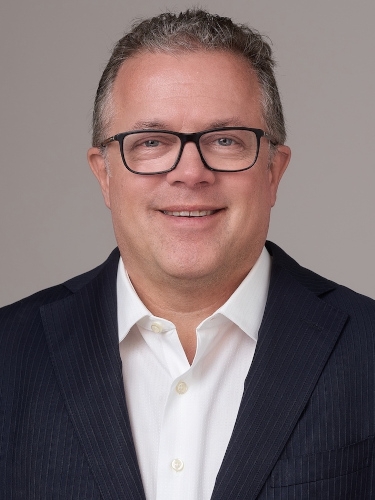
“We are always looking for ways to increase our Canadian exposure,” he says, “but we haven’t really found a path yet for that to happen because of long-standing structural barriers to growth here.”
As demand for semiconductors and other hardware necessary for data centres supporting AI’s global expansion continues to accelerate, Canada is uniquely positioned with energy and other resources required to support potentially unprecedented growth.
What’s more, the war in Iran has upended how the world does business. “Global supply chains are upside down right now,” Jessiman says, “but if we act shrewdly this can be an opportunity as opposed to a problem.”
Jessiman is somewhat skeptical that will happen, given how Canada has been notoriously slow in approving major projects for high-demand commodities destined for international markets. “If you talk to anybody who’s allocating capital internationally and considering Canada, most sum up our country in two words: regulatory bottlenecks.”
Jessiman says the country cannot compete if it continues to take years to approve a project when other jurisdictions are approving similar ones in a matter of months. Still, he says there is cause for some optimism, especially in the wake of events like the recent Canada Investment Summit, which secured $500 billion in new commitments from the private sector. As well, the new federal Major Projects Office may speed up approval timelines, Jessiman says.
Such structural changes, however, will take time to made a positive impact. In the meantime, Jessiman’s family office is boosting portfolio exposure modestly to international markets. It is a response to Asia’s high growth potential and, more broadly, AI’s benefits seeping into the operations of international businesses across all industries, boosting their productivity and potentially improving profitability.
“We have introduced more international exposure over the last nine months,” Jessiman says, noting the allocation now accounts for 10 per cent of the portfolio. As well, third-party investment managers the family office works with have steadily increased global exposure.
Jessiman believes more Canadian exposure is coming, too, provided the positive changes under way continue to accelerate so the nation can seize the massive economic opportunity ahead.
“Canada can be competitive,” he says, “but we’ve got to create an environment where we can properly leverage our natural strengths.”
Joel Schlesinger is a Winnipeg-based freelance writer who has written for Canadian Family Offices since 2021. Specializing in investment, wealth advice, real estate and personal finance, he is also a regular columnist for the Winnipeg Free Press, and his work regularly appears in The Globe and Mail, Calgary Herald and Edmonton Journal.
Get our new quarterly newsletter about real estate: Canadian Family Offices’ new newsletter will bring you key insights, trends and expert perspectives. Click here to subscribe.
Please visit here to see information about our standards of journalistic excellence.